
Weekly Credit Crunch 19 October 2026 🌟
☕ A Little Inspiration Before This Week's Credit Crunch!
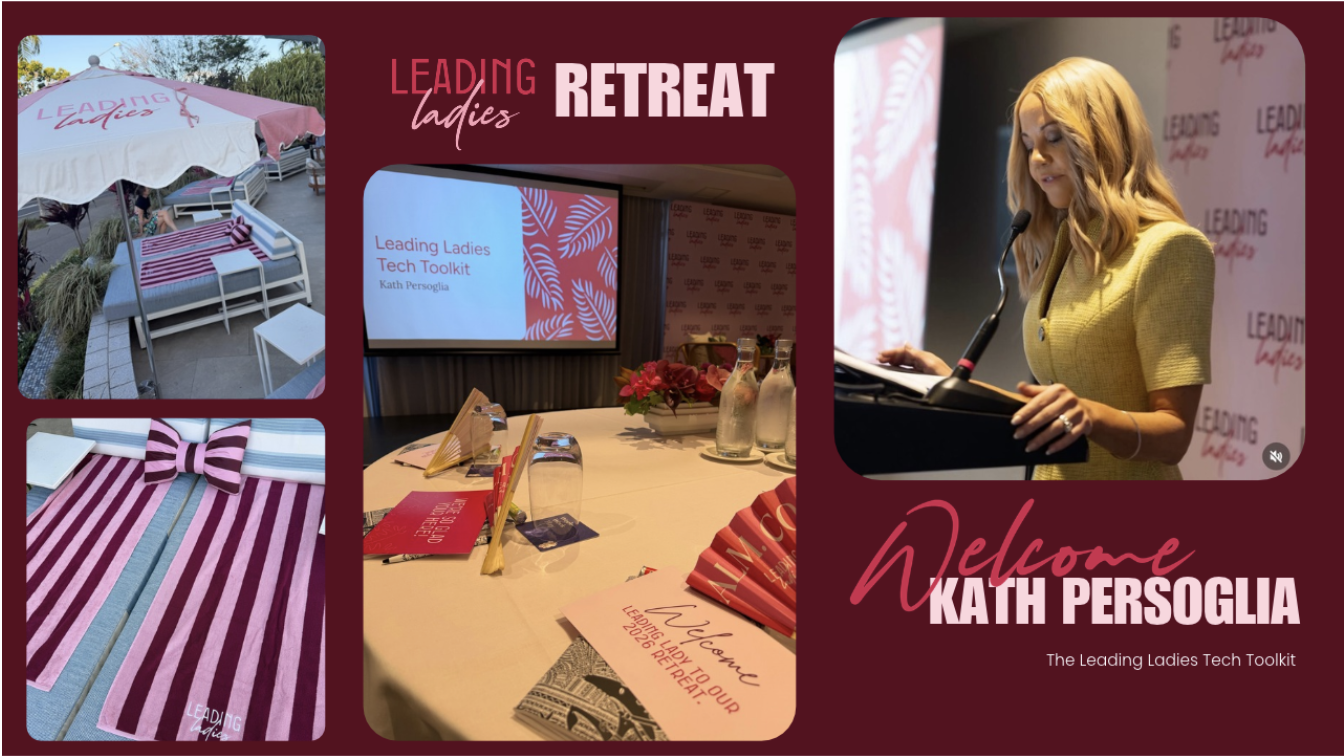
Last week I had such a lovely time up in Cairns at the Loan Market Leading Ladies Conference. There really is something special about getting a room full of women in finance together to share ideas, experiences and have some honest conversations about the ups and downs of life and business.
I was fortunate enough to have the opportunity to speak about something I'm really passionate about AI and technology, and was joined on stage by three wonderful female brokers who generously shared some of their favourite tech hacks, both in business and everyday life. I think we all walked away with a few new tricks up our sleeves!
There were some fantastic speakers throughout the event, but one of my personal highlights was Chelsea Pottenger. We spent two hours with Chelsea, and I could have happily listened for another two!
She shared so many simple, practical reminders about looking after ourselves, from the importance of sleep, getting outside for some morning sunlight, moving our bodies and taking a break from our screens, to nutrition, podcasts and the power of a positive mindset. All those little things we know we should be doing but somehow get lost in the busyness of everyday life!
But what really stuck with me was her message about having a growth mindset.
"Practice makes progress."
And my personal favourite...
"If you're not good at something, you're just not good at it YET!"
Such a simple little word, but what a difference it makes.
It really resonated with me, particularly when I think about how quickly our industry is changing. Whether it's learning to use AI, trying something new in business or just finding a better way to juggle everything life throws at us, none of us have all the answers. We're all learning as we go.
I came home feeling grateful for the opportunity to connect with so many lovely women, share a few ideas and learn plenty of new things myself.
And if there's one little reminder I wanted to pass on this week, it's that we don't have to be good at everything straight away. We just have to be willing to give things a go.
Anyway, enough from me! ☕ Let's get into this week's Credit Crunch — there's plenty happening in lender policy to keep us on our toes! 👇
🏦 LENDER POLICY & PRODUCT UPDATES
🔵 Bluestone for LMG | Expanded Lending Policy
Bluestone has introduced several policy and assessment improvements, offering greater flexibility across servicing, income verification and security requirements.
Key changes:
- Comprehensive Credit Reporting (CCR): Now used for all debts, with the most recent 6 months reviewed for mortgages and 1 month for personal loans and credit cards.
- Full Doc Verification: Now requires just 1 year of tax returns and Notice of Assessment (NOA).
- Casual Employment: Less than 6 months' employment can be considered under Specialist/Specialist+.
- Higher Loan Limits: Lending up to $5 million for Prime loans below 70% LVR in metropolitan locations, with a maximum total exposure of $15 million.
- Larger Land Sizes: Maximum acceptable land size increased to 10 acres (4 hectares).
- Multiple Dwellings: Up to 4 dwellings permitted on a single title.
- Development Approval (DA): Properties with an active DA may be accepted, subject to a statutory declaration confirming the borrower will not act on the approval.
🔵 Firstmac | Bridging Finance Just Got Better!
Firstmac has enhanced its Bridging Loan offering, giving brokers more options for clients looking to purchase their next home before selling their existing property.
What's changed?
- Bridging periods of up to 12 months for all applications.
- End-debt servicing only, where applicable.
- Interest capitalised during the bridging period.
- No repayments required during the bridging period.
- Expanded eligibility to Category 2 postcodes.
- Cash-out now available.
- Reduced establishment fee.
- Seamless transition to the end debt.
- Improved broker commissions across the bridge and end debt.
- Competitive fixed interest rate.
🔵 Macquarie | Improved Servicing, Essential Services & Construction Policy
Macquarie has announced several policy enhancements, including increased rental income for servicing, expanded essential services eligibility and more flexible construction lending requirements.
🏡 Rental Income – Increased to 80%
- Rental income shading reduced from 25% to 20%, allowing 80% of rental income to be used for servicing (previously 75%).
- The 80% allowance is inclusive of the 15% rental expense provision.
👩⚕️ Expanded Essential Services Occupations
Additional frontline occupations now included:
- Disability support workers.
- Aged care workers.
- Aviation workers, including pilots and flight attendants.
🏗️ Construction Lending – Higher Inspection Threshold
- Progress payment inspections will now only be required for construction contracts of $1 million or more.
- Previously, inspections were required for contracts of $600,000 or more.
💻 ApplyOnline Enhancements
From 26 October 2026, brokers will be able to:
- Nominate partial repayments on existing liabilities.
- Identify existing liabilities being paid out using the borrower's own funds.
🔵 ME Bank | CCR & Hardship Assessment Changes
ME Bank has simplified its assessment requirements to better align with Comprehensive Credit Reporting (CCR).
Key changes:
- Hardship Assessment: For non-CCR facilities, the required assessment period has reduced from 12 months to 6 months.
- Unsecured Debt Refinancing: Eligible borrowers refinancing unsecured debts from non-CCR lenders may now be considered with less than 6 months' repayment history, provided they demonstrate satisfactory account conduct and hold a home loan with a CCR-participating lender.
Important LMI reminder:
ME Bank has also reinforced that Lenders Mortgage Insurance premiums are non-refundable.
Customers will not receive an LMI refund if they:
- Repay or discharge their home loan within 2 years of settlement.
- Reduce their LVR below 80% through repayments, property value increases or refinancing.
🔵 NAB | Serviceability Calculator & LMI Updates
NAB has announced two important calculator updates.
- New Serviceability Calculator – Effective 23 October 2026
NAB is updating its Household Expenditure Measure (HEM) values to align with the latest APRA requirements.
- New calculator version: V66.
- Available from Friday 23 October 2026.
- Required for new home lending applications submitted after 12:00 am AEDT on 23 October 2026.
- LMI Premium Calculator – Increased Loan Limits
NAB's refreshed QBE LMI Premium Calculator can now calculate eligible LMI premiums for loans up to $5 million.
- Manual quotes are no longer required for eligible loans above $2.5 million.
- Calculator login details are no longer required.
- Complex scenarios, including business lending, may still require manual quotes.
Where to find it: NAB Broker Portal → Forms & Calculators → LMI Premium Calculators → Calculating LMI.
🔵 Resimac | Greater Flexibility for Alt Doc, Casual & Rental Income
Resimac has introduced several policy enhancements, simplifying verification and broadening eligibility across common lending scenarios.
Key changes:
- Prime Alt Doc – Reduced ABN Registration Period
Eligible applicants can now be considered with an ABN registered for a minimum of 18 months, subject to applicable trading history, income verification and industry experience requirements.
- Casual Employment Income
Casual income can now be assessed using 48 weeks of income, providing a more consistent approach to income assessment.
- Private Rental Income Verification
Private rental income can now be verified using a current signed tenancy agreement, without requiring additional bank statements or tax returns.
All applications remain subject to Resimac's credit assessment criteria.
🔵 Skip by LMG | More Borrowers, More Locations, Less Paperwork!
Skip by LMG has introduced several improvements in response to broker feedback.
- Bridging Visa Borrowers
Married borrowers holding a bridging visa may now be eligible for a Skip by LMG loan.
Refer to the Borrower Criteria Summary for the full list of accepted visas.
- Expanded Lending Locations
Skip has extended lending eligibility to:
- Bunbury, WA
- Townsville, QLD
- Maitland, NSW
Skip is also transitioning from postcode-based to suburb-based eligibility criteria, making it easier to identify acceptable locations.
- Simplified Verification of Identity (VOI)
Borrowers now only need one form of photo identification:
- Driver's licence; or
- Passport.
The previous requirement for a second form of identification has been removed.
🔵 Wave Money | Alt Doc Family Guarantee
Self-employed first home buyers who need family support may have another option with Wave Money's Alt Doc Family Guarantee.
This product enables eligible borrowers to leverage parental equity where traditional income verification may not be available for the borrower, guarantor or both.
Key features:
- Alt Doc borrowers considered.
- Alt Doc guarantors considered.
- Limited guarantee structures available.
- Guarantor liability limited to the guaranteed amount.
- Up to 80% LVR for Alt Doc lending.
📢 INDUSTRY & OPERATIONAL UPDATES
🟠 Suncorp Bank | Transition to ANZ – Important Customer Changes
As Suncorp Bank prepares to transition customer loans and accounts to ANZ, brokers should be aware of several changes that may affect existing clients.
What's staying the same?
- Loan balances, including accrued interest, at the date of transition.
- Interest rates applicable at the time of transition, although variable rates and margins may change subsequently under the loan terms.
Key changes to watch:
Principal & Interest Repayments
Customers who have made additional repayments and have funds available in redraw may see their minimum repayments increase after transitioning to ANZ.
Depending on the outstanding balance, advance repayments and remaining loan term, the increase could be significant.
Offset Accounts
Only one offset account can be linked to a home loan.
Existing sub-accounts will become ANZ transaction accounts and will no longer offset the loan. Customers may need to consolidate funds into their main Everyday Options Account to retain their full offset benefit.
Interest Only Loans
No immediate repayment changes unless the loan subsequently converts to Principal & Interest.
Construction Loans
- A 24-month construction completion limit will apply from the date of transition.
- Loans will switch to Interest Only during this period.
- Redraw will not be available during construction.
- Loan terms may be amended.
Company Borrowers
Home loans held in a company name will no longer have access to redraw.
Loans with Nil Balances
Loans with no outstanding balance will be closed unless the customer takes action.
Broker Commissions & Accreditation
- Eligible trail commissions will continue after transition.
- Brokers holding both Suncorp Bank and ANZ accreditation will be best positioned to support affected customers.
- Brokers without ANZ accreditation should review their accreditation requirements.
Timing: ANZ will communicate with customers about their transition dates and the applicable changes.
💡 Broker takeaway: This is an important opportunity to proactively review affected clients, particularly those with multiple offset accounts, substantial redraw balances, construction loans or company-held lending.
For more information, visit the Suncorp Bank Broker Portal or search Move to ANZ on the Suncorp Bank website.
🎓 BROKER EDUCATION & POLICY LEARNING BITES
🧠 Westpac | Apportioning Household Expenses & Common Debts
Did you know Westpac has policy provisions that may allow borrowers to apportion certain household expenses and existing debt repayments?
Depending on the scenario, this could make a significant difference when assessing an applicant's borrowing capacity.
Policy Reference: 03.17 – Serviceability Assessment
Option 1: Apportioning Spousal Household Expenses & Common Debts
Section 2.5.1
Westpac may allow serviceability to be assessed using the borrower's apportioned share of:
- Household living expenses shared with their spouse.
- Repayments on existing common debts, commitments and liabilities.
Option 2: Apportioning Common Debts
Section 2.5.2
Westpac may allow serviceability to be assessed using the borrower's apportioned share of repayments for existing common debts, commitments and liabilities.
💡 Broker tip: When assessing a borrower with a spouse or joint financial commitments, don't automatically assume that all shared expenses or joint debt repayments must be included in full.
Review Westpac's apportionment provisions to determine whether a more appropriate assessment is available.
Both options are subject to applicable credit policy and serviceability requirements. Refer to Westpac Policy 03.17 for full eligibility criteria.
📅 UPCOMING BROKER TRAINING & WEBINARS
🏦 CBA | Fast-Tracking First Home Buyer Applications
Join CommBank for a practical session focused on helping first home buyers navigate the lending process.
What you'll learn:
- Key first home buyer eligibility considerations.
- Available first home buyer lending options.
- Common application and documentation requirements.
- Tips to help applications progress more smoothly.
You'll also have the opportunity to meet the CommBank Relationship Managers who support brokers.
🏦 Firstmac | Bridging Finance National Webinar
Want to understand Firstmac's updated bridging product and how to structure your clients' next purchase?
Join Firstmac for a product deep dive covering the enhanced Bridging Loan offering.
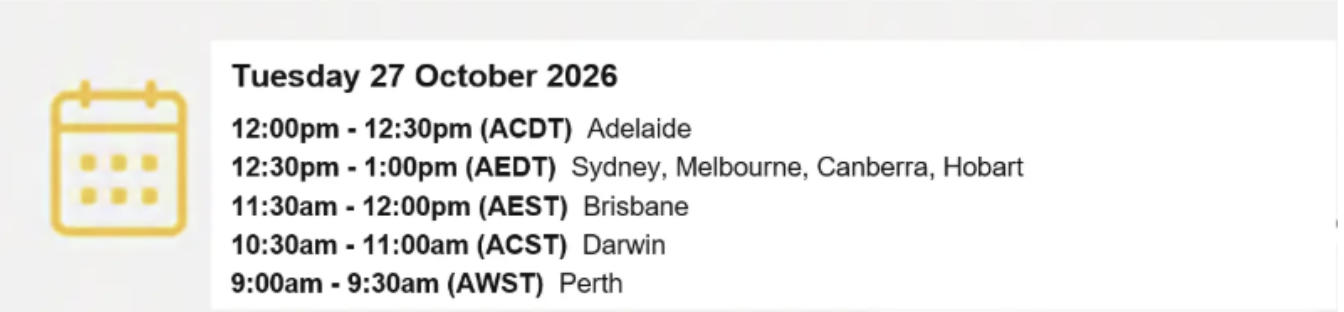
Thursday 22 October 2026
Time: 11:00 am – 12:00 pm AEST
Helpful broker tools
Firstmac also offers two tools to assist with bridging scenarios:
- Bridging Tool: My Tools → Documents. Model the proposed loan structure and receive an indication of end debt and other key loan metrics.
- Bridging Servicing Calculator: Broker Tools → Servicing → Bridging. Assess servicing outcomes and identify suitable options for your clients.
CREDIT COACHING | Excluding Company & Business Debts from Serviceability
Excluding company and business liabilities was the most frequently searched lending scenario inside The Brokers’ Bible last month and it's easy to understand why!
For self-employed clients, business loans, commercial mortgages, equipment finance and other company liabilities can significantly impact borrowing capacity.
The good news? Some lenders allow these commitments to be excluded from personal servicing, but the rules vary considerably.
Key policy considerations for brokers
- Who actually holds the debt? Is the liability held in the client's personal name, a company, trust or partnership? The legal borrower and entity structure can determine whether the debt can be excluded.
- Is the business self-sufficient? Some lenders will exclude company liabilities where the business can demonstrate it generates sufficient income to meet its own repayments without relying on the applicant's personal income.
- Are you using company profits to service the new loan? Some lenders only permit company debt exclusions when the applicant is assessed using personal income or director's wages, rather than underlying company profits.
- Has the debt already been accounted for in the financials? Lenders may exclude liabilities where the associated interest or repayments have already been factored into the business income assessment. This avoids effectively counting the same commitment twice.
- Watch the interest addbacks! Some lenders will only exclude a business liability where the associated interest has not been added back to assessable income. Adding back the interest while excluding the repayment could overstate borrowing capacity.
- What about newly established business debts? Liabilities taken out after the most recent financial statements may need to be included separately, even where existing business debts can be excluded.
- Does a personal guarantee change things? Some lenders distinguish between company liabilities and debts personally guaranteed by a director. Others have specific policies for director-only guarantors versus guarantors whose income is required for servicing.
- Are there other companies or trusts? Where a client has interests in multiple entities, some lenders may disregard liabilities from separate, financially self-sufficient entities, particularly where no income from those entities is being used.
- Don't forget director/shareholder loans. Amounts owed by directors to their companies can be treated differently from external business debts. Some lenders apply specific assessment rules depending on the ownership structure and balance-sheet treatment.
- Evidence can make all the difference. Depending on lender policy, financial statements, tax returns, accountant confirmation or broker commentary may be required to demonstrate that the business can meet its ongoing commitments.
The key takeaway
A company liability doesn't automatically mean a personal servicing liability.
The opportunity lies in understanding how the lender assesses business income, where the debt sits, whether the business can support its own commitments and what evidence is required.
Before ruling out a client's borrowing capacity, check whether the lender allows company or business debts to be excluded — and importantly, under what conditions.
The Brokers’ Bible has a dedicated policy module covering lenders that may exclude company and business debts from serviceability. Jump into the module HERE
That's a wrap for this week's Credit Crunch! ☕
Remember, sometimes it's the smallest policy change that opens the door to a deal you thought wasn't possible.
Stay curious, keep learning and never underestimate the value of knowing your lender policy!
See you next week!
Kath
NOT A MEMBER YET?
Join today with a 14-day free trial — month-to-month, cancel anytime.
Individual memberships start from $57 + GST per month and give you 24/7 access, on desktop and via our mobile app, plus your always-on research sidekick BrokerChat.AI.
Smarter research. Faster answers. Less stress.
What are you waiting for?

