
Weekly Credit Crunch 5 October 2026 🌟
Another week, another round of policy changes, product updates and lender movement.
This week we’ve got self-employed servicing changes, Centrelink income updates, a new 40-year loan term, credit-score flexibility, changes to Suncorp Bank lending and a few useful broker tools and webinars.
Here’s what you need to know.
🏦 Bank of Sydney
Business Lending Policy Updates
A few positive changes for business lending:
-
The minimum loan size requiring an annual review has increased from $1 million to $3 million.
-
Loans to self-employed borrowers through a corporate entity no longer require a company guarantee where the loan is for consumer purposes.
SME Lending
Eligible Special Purpose Vehicles (SPVs) can now access SME lending, subject to conditions including:
-
Majority of income derived from a trading business
-
SPV and trading business having the same owners and forming part of the wider group
-
A guarantee linking the trading entity to the loan facility
-
A first-ranking GSA may be required where the trading business provides the primary income source
Servicing win: All depreciation shown in the borrower’s most recent tax return may now be added back for SME servicing, subject to Credit assessment.
🏦 Granite Home Loans
NEW: Loan Terms Up to 40 Years
Granite has launched its Extended Home Loan, offering loan terms of up to 40 years.
Key policy highlights:
-
Owner Occupied and Investment lending
-
Purchase, refinance and construction
-
Up to 95% LVR, inclusive of applicable risk fees
-
Company and Trust borrowers: maximum 80% LVR
-
Servicing may be assessed over up to 35 years, rather than the traditional 30 years
-
Full 40-year term available up to age 45
-
Available term reduces incrementally for applicants aged 46–50
-
No separate investor age restriction noted
-
Interest Only up to 5 years Owner Occupied / 10 years Investment
-
Variable rates only
-
Residential security only
-
Loan sizes from $150,000 to $3.5 million, subject to location and lending criteria
-
PAYG, self-employed, Company and Trust income may be accepted
-
100% offset, redraw and unlimited additional repayments available
⚠️ Refinance Restriction
Standard refinances from a 30-year loan are generally permitted.
However, loans originally arranged or managed by ColCap Financial Group, Origin MMS or associated managers/partners cannot generally be refinanced into Granite’s 40-Year Extended Home Loan.
🏦 Resimac
Credit Score Not Perfect? Don’t Automatically Rule the Deal Out
Resimac has reinforced that it does not rely on credit score alone. Instead, it assesses the borrower’s overall scenario and the story behind the credit file.
That means scenarios worth discussing can include:
-
Clients declined by a major due to credit score
-
Missed repayments within the last 12 months
-
Defaults
-
Judgements, writs or summons
-
Discharged bankruptcy
-
Current bankruptcy
Where Prime isn't suitable, Resimac also offers its Clear, Plus and Assist Specialist tiers depending on the severity of the credit history.
Another important point: Specialist pricing does not necessarily need to be permanent. Where the borrower maintains repayments for 12 months, they may automatically revert to Prime rates.
Broker Takeaway
Don’t automatically write off a borrower because a major has declined them on score. Understand the story behind the credit file and workshop the scenario before assuming the deal is dead.
🏦 Skip by LMG
Credit Is About the Story — Not Just the Checkbox
Skip has shared some recent examples where the borrower didn’t fit neatly into a standard policy box, but there was a clear story behind the application.
Examples included:
-
New migrants with permanent employment but short Australian job tenure
-
Borrowers who had rebuilt financially after bankruptcy
-
First home buyers using a recently received family gift
-
An experienced employee returning to work after a six-month career break
-
A childcare worker returning to casual employment following maternity leave
The common thread?
Understand why the borrower looks the way they do on paper.
Short tenure, limited savings or a career gap doesn’t always equal instability. Sometimes it simply needs context.
Skip is encouraging brokers to workshop these scenarios before ruling them out — including providing a redacted CCR where appropriate.
🏦 Suncorp Bank
🚨 Important: Suncorp Bank Lending Is Closing to New Applications
As part of Suncorp Bank’s transition to ANZ, Suncorp Bank will stop accepting new lending applications from Wednesday, 7 October 2026.
What Brokers Need to Know
Any application that has not yet been submitted should be lodged before Wednesday, 7 October 2026.
From that date:
-
Suncorp will no longer accept new lending applications
-
Existing applications received prior to the cut-off will continue to be assessed
-
Existing customers can continue to access most normal banking services
-
Credit-critical variations requiring a new credit assessment may need to be completed through ANZ or another lender
Key Inflight Application Dates
Tuesday, 27 October 2026
Stop Loan Decisioning and Loan Documentation Issuance. Final approval and loan documentation must be issued by this date.
Saturday, 26 December 2026
Stop Settlement/Fulfilment. This is the final date eligible submitted loans or services requiring a new account or letter of offer can settle and be fulfilled.
🎓 Education & Webinars
A few useful broker education sessions coming up this month.
🏦 MA Money – Behind the Scenes with Credit
Want to know what happens after you submit a deal and what can help you get a faster decision?
MA Money is running a practical session with Stephen Begnell, Head of Lending, and Paul Liccione, NSW/ACT BDM, taking brokers behind the scenes of their credit process.
They’ll cover:
-
How MA Money’s streamlined credit process works
-
What Credit is looking for when assessing your application
-
Tips for packaging a strong submission
-
What can delay a decision beyond two business days
-
Real broker experiences and scenarios
-
Live Q&A
📅 Wednesday, 14 October 2026
⏰ 12:00pm–1:00pm AEDT
🎓 1 CPD point
A great session if you want to better understand how to package MA Money deals for a cleaner, faster credit assessment.
🏦 NAB – Commercial Broker Metro Webinar
NAB is hosting a Commercial Broker Metro session looking at what’s shaping the business market and what it means for your clients.
Hosted by Chris Thomas, Executive – Commercial Broker & Equipment Finance Sales, alongside NAB executives and Chief Economist Sally Auld, the session will cover:
-
The latest economic outlook
-
Key trends affecting Metro businesses
-
What business customers are currently focused on
-
Growth opportunities and emerging trends
-
How NAB’s bankers, Credit specialists and industry experts can support your clients
-
The role brokers play in connecting customers with the right expertise and solutions
-
Live Q&A
📅 Thursday, 15 October 2026
⏰ 3:00pm AEDT
🎓 CPD points may be available
A useful session for brokers wanting a broader view of the commercial market and the economic trends shaping business lending decisions.
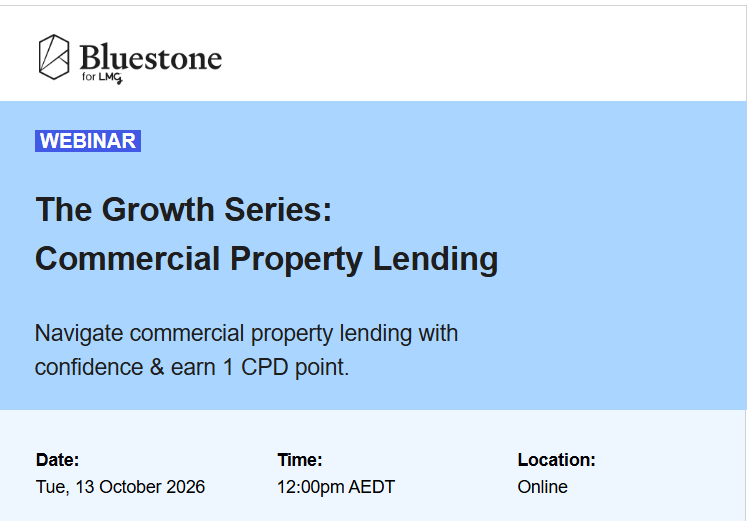
Join Bluestone’s Head of Non-Standard Lending, Richard Chesworth for the first session of The Growth Series. Our new broker education webinar series designed to help you uncover new opportunities to help you grow your business.
- Discover how commercial property lending can create new opportunities for your business
- Learn how to recognise commercial lending needs within your existing client base
- Build confidence navigating common commercial property scenarios
- Gain practical insights you can put into action with clients straight away
🎓 Kath’s Credit Coaching
Using Centrelink Income? Don’t Just Ask “Does the Lender Accept It?”
Centrelink income can absolutely help with servicing, but this is one of those areas where “accepted at 100%” does not mean “accepted without conditions.”
The broker’s job is to understand exactly what the payment is, how long it will continue, how much of the client’s overall income it represents, and whether the proposed loan fits within policy.
Broker Watch-Outs:
100% acceptance does not automatically mean unrestricted use. Brokers should still check:
-
Permanency: Most lenders require the benefit to be ongoing/permanent, often for a minimum of 5 years.
-
Income Share Caps: Many cap combined government income at 50% of total income
-
Dependant Age Limits: Family Tax Benefit (FTB) is typically restricted to children under 11–15, depending on the lender.
-
JobSeeker/Newstart: Universally unacceptable across the panel.
-
Sole Source: Whether the income can be the sole or primary income source - Several lenders will not allow government income to be the sole or predominant income source.
- Whether LVR restrictions apply where government income forms the majority of total income (remember LMI credit assessment)
- Product or loan-purpose restrictions, particularly for investment and cash-out lending.
Start with the income itself
Before running servicing, ask your client:
-
What exact Centrelink or government payment are you receiving?
-
When did you start receiving it?
-
Is the payment ongoing, permanent or temporary?
-
How much do you receive and how often?
-
Are there any additional supplements included?
Do not rely on the client saying, “I get Centrelink” or “I get a carer payment.” The exact payment type matters. A Carer Payment and a Carer Allowance, for example, may be treated very differently.
Check how long the income will continue
One of the biggest policy issues is continuity. Many lenders want to see that the income is expected to continue for a reasonable period, and 5 years is a common benchmark.
For Family Tax Benefit or parenting-related income, you need to understand:
-
How old is each dependant?
-
Which child is the payment linked to?
-
When will the benefit reduce or cease?
-
Will enough income remain over the required period?
A client may be receiving the income today, but if a dependant is close to an age cut-off, the lender may not be prepared to use all of it.
Understand how much of the client’s total income is government income
This is a big one.
Ask:
-
Does the client have PAYG, self-employed, rental, investment or superannuation income as well?
-
Is Centrelink the sole source of income?
-
Roughly what percentage of total household income comes from government payments?
Some lenders are comfortable with government income only as supplementary income, while others place limits on how much of the overall servicing income can come from government benefits. So even if the income is accepted at 100%, the deal may still fail because too much of the client’s total income is coming from that source.
Know the purpose of the loan
Always establish this early:
-
Owner-occupied purchase?
-
Refinance?
-
Investment property?
-
Equity release?
-
Cash-out?
-
Debt consolidation?
Government income treatment can change depending on the loan purpose. A payment that is perfectly acceptable for an owner-occupied refinance may not necessarily be treated the same way for investment lending or a substantial cash-out request.
Watch the LVR
If the majority of the client’s income comes from government benefits, some lenders may become more conservative around maximum LVR.
So before assuming the client can borrow at 80%, 90% or above, check whether the income type creates a lower LVR ceiling.
Family Tax Benefit needs extra care
For FTB A and B, do not stop at the current Centrelink amount.
Ask:
-
How old are the dependants?
-
How long will the payment continue?
-
Is the payment received fortnightly or annually?
-
Is the client receiving both FTB A and B?
-
Are there any shared-care arrangements?
This is one of the most common areas where brokers can accidentally overstate income.
Child support needs its own verification
If child support is being used:
-
Is it formally assessed or privately arranged?
-
How old is the child?
-
How long will the payments continue?
-
How long has the client been receiving them?
-
Are the payments consistent?
You want evidence of both the current entitlement and the actual receipt of funds.
Documents I would collect upfront
My recommendation is to collect everything before running final servicing:
-
Centrelink Income Statement — all pages, as current as possible
-
3–6 months bank statements showing the income credits
-
Department of Veterans’ Affairs letter, if applicable
-
Child Support Assessment Notice, if child support is being used
-
Supporting evidence for any other income being used, such as PAYG income, business income, rental income or superannuation
Broker Tip
The Centrelink Income Statement from myGov should be your starting point.
It usually confirms:
-
the payment type
-
current payment amount
-
payment frequency
-
supplements
-
ongoing or future entitlements
Download it as close to submission as possible. In practice, a recent Centrelink statement paired with bank statements showing the actual credits will cover a large part of your verification work.
The big broker watch-outs
Before you lodge, make sure you have checked:
-
Is this payment actually acceptable?
-
Can it be the sole or primary source of income?
-
Does the lender cap government income as a percentage of total income?
-
Will the income continue long enough?
-
Are there dependant age restrictions?
-
Is the payment permanent, stable or temporary?
-
Does the loan purpose create any restrictions?
-
Does the LVR need to be reduced? Check LMI policy also.
-
Are you using the correct payment type and not assuming similar Centrelink payments are treated the same way?
-
Have you evidenced both entitlement and actual receipt?
Kath’s Recommendations:
Do not start with:
“Does the lender take Centrelink?”
Start with:
“What exact payment is it, how long will it continue, how much of the client’s total income does it represent, and does it fit this loan purpose?”
That is the difference between simply reading policy and actually structuring the deal properly before submission.
That’s it for this week!
I hope everyone enjoys the public holiday today and manages to sneak in a little extra downtime — whether that’s with family, friends or simply avoiding the laptop for a few hours!
As always, jump into The Brokers’ Bible for the full lender policy, criteria and supporting detail before submitting your deal.
That’s it for this week, enjoy the public holiday and I’ll see you next Monday.
NOT A MEMBER YET?
Join today with a 14-day free trial — month-to-month, cancel anytime.
Individual memberships start from $57 + GST per month and give you 24/7 access, on desktop and via our mobile app, plus your always-on research sidekick BrokerChat.AI.
Smarter research. Faster answers. Less stress.
What are you waiting for?

